
Reading the Fed (dot plot & communications)
Educational only. Fed communications are teaching materials here—not a promise of the next hike/cut and not a trade signal.
Site vs Telegram
How-to-read explainers live here. Meeting-day decoding belongs on Telegram: Macro Simplified on Telegram.
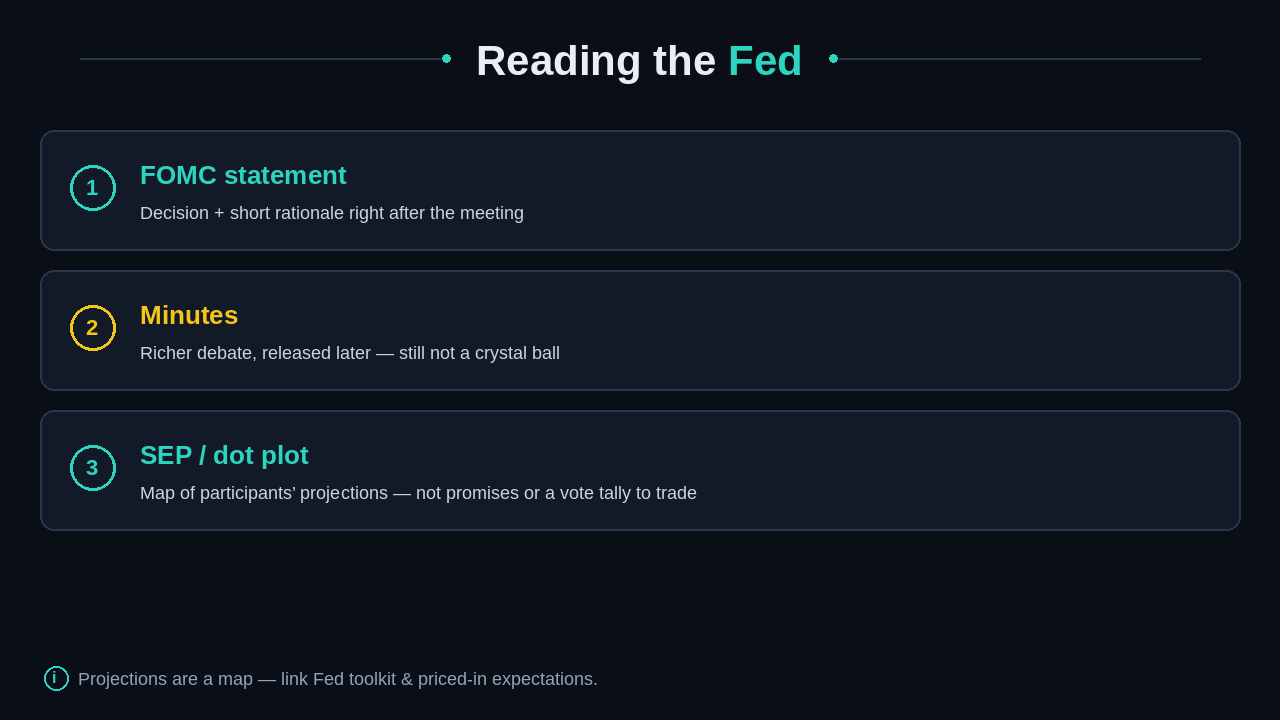
Diagram: statement → minutes → SEP/dots as a projection map — not promises.
Start with the toolkit
If policy rate, balance sheet, and forward guidance still blur together, read The Fed toolkit first. This page is about how to read the paperwork and charts the Fed publishes around FOMC meetings.
1. The FOMC statement
Right after many meetings, the committee releases a short statement: the decision (target range, etc.) plus compressed rationale and guidance language.
Beginner habit:
- What changed vs last time (rate, wording, balance-sheet language)?
- What stayed the same on purpose?
- What does this imply for the path—without turning it into a position?
Press conferences add tone. Still educational context only.
2. The minutes
Minutes arrive later and sketch the range of debate—what participants emphasized on inflation, jobs, risks, and tools. They are richer than the statement and still not a crystal ball. Markets sometimes react; priced-in expectations still govern how “surprising” any paragraph feels.
3. SEP and the dot plot
On scheduled meetings, the Summary of Economic Projections (SEP) gathers participants’ projections for growth, unemployment, inflation, and the policy rate.
The famous dot plot charts each participant’s appropriate policy-rate projection by year. Teaching rules:
- Dots are projections, not promises
- Dots are not a committee vote already taken for future meetings
- The median dot is a headline shortcut—dispersion matters too
- Economy evolves; projections get rewritten
Pair dots with market pricing using the surprise-vs-level habit in Priced in / expectations. Process for the day: Event playbook.
Communications beyond meeting week
Speeches, testimony, and interview remarks are also forward guidance channels. One speaker is not “the Fed” by themselves—weight the chair and the breadth of messages, still without trading the soundbite.
Next reads
- The Fed toolkit — tools behind the words
- Priced in / expectations — why markets move on surprises
- Event playbook — calm FOMC-day process
- Interest rates and yields — market yields vs policy rate
- The yield curve for beginners — path pricing across maturities
Related reads
Telegram
FOMC days decoded live: Join Macro Simplified.